Мы используем cookie
Настройки cookie
Обязательные cookie всегда включены, так как они нужны для корректной работы сайта.
Аналитические cookie Яндекс.Метрики и статистики платформы Tilda можно включить или отключить. Они помогают нам видеть статистику посещений и улучшать сайт.
Аналитические cookie Яндекс.Метрики и статистики платформы Tilda можно включить или отключить. Они помогают нам видеть статистику посещений и улучшать сайт.
Family Wealth Plan / HFWP: How a Financial Plan Becomes Part of the Overall Architecture
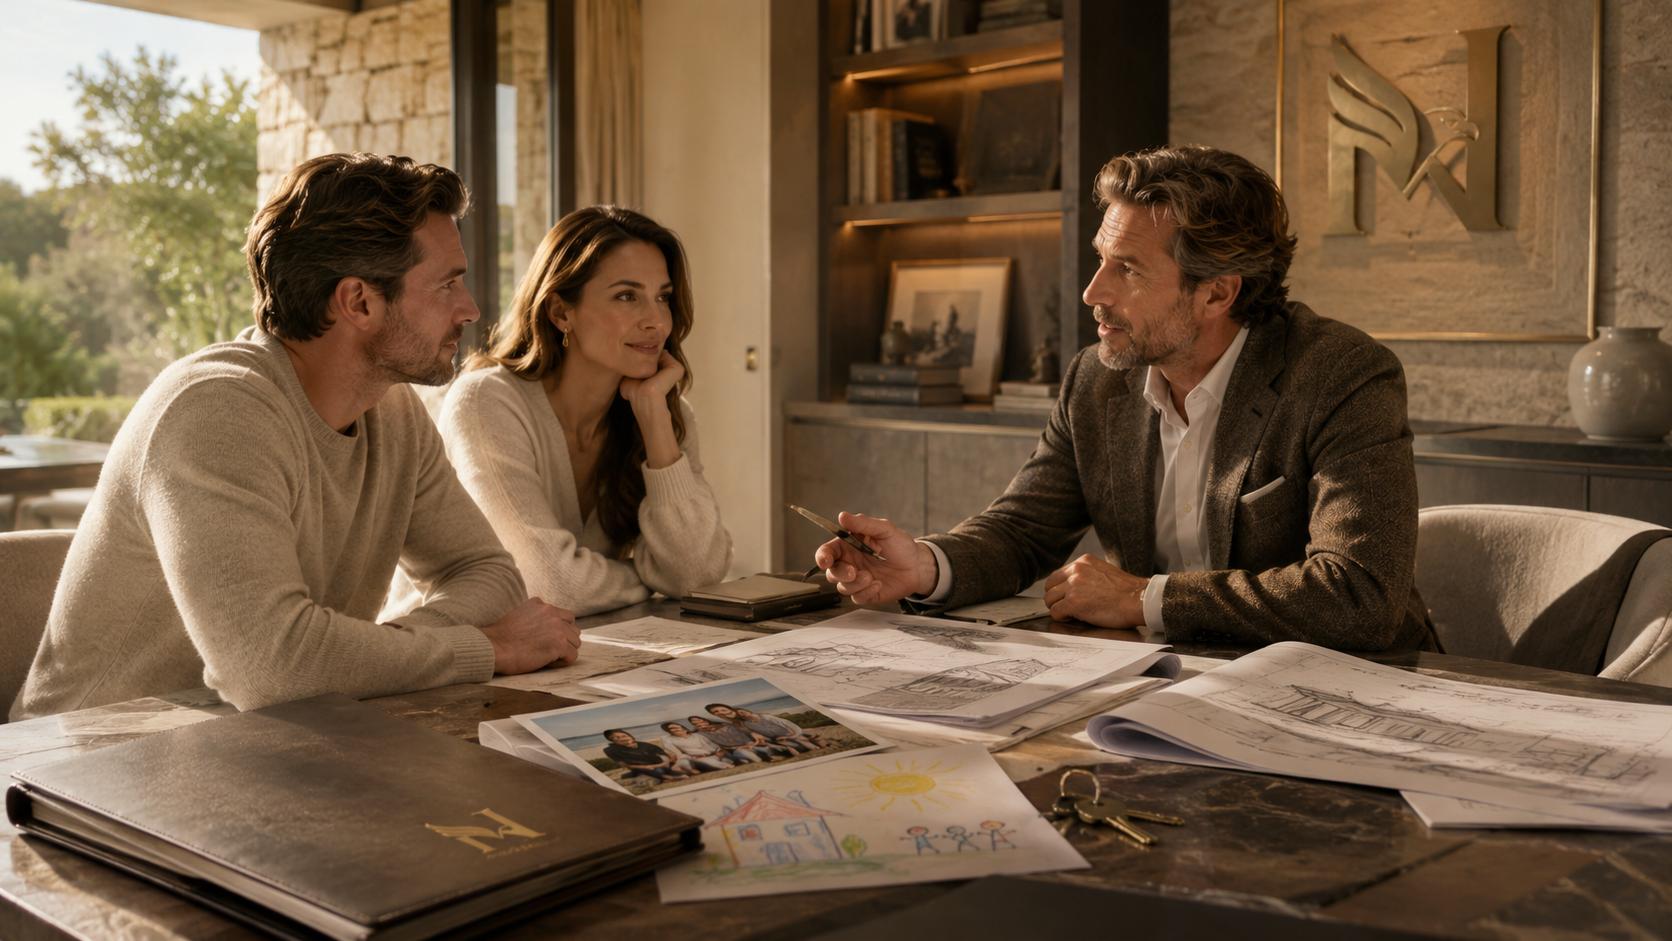
Gathering scene.
The family comes with a neat request: “We need a financial plan.” Clear words are heard in the conversation: children’s education, reserves, investments, pensions, real estate, business, protection.
At the end of the first hour, one of the partners looks at the table and asks: “Is this really what we want? Or what we used to want?”
After this question the conversation changes.
One partner talks about freedom in five years. The other wants security now. The business periodically takes the family's money, but in calculations this is called a temporary movement. Children are included in the plan as expenses, but not as people who will one day have to make decisions. There are documents, but it is unclear who and how will use them during a crisis.
And at some point it becomes clear: the family really needs a plan. But not only financial.
The family comes with a neat request: “We need a financial plan.” Clear words are heard in the conversation: children’s education, reserves, investments, pensions, real estate, business, protection.
At the end of the first hour, one of the partners looks at the table and asks: “Is this really what we want? Or what we used to want?”
After this question the conversation changes.
One partner talks about freedom in five years. The other wants security now. The business periodically takes the family's money, but in calculations this is called a temporary movement. Children are included in the plan as expenses, but not as people who will one day have to make decisions. There are documents, but it is unclear who and how will use them during a crisis.
And at some point it becomes clear: the family really needs a plan. But not only financial.
A financial plan answers important questions. How much do you need to save? By what date? With what profitability? At what risk? How much money is needed for the goal? What reserve should there be? What needs to be done every month.
But the family has issues that don't fit into a conventional financial model. Who will carry out this plan if the main person falls out of the system? What money should you not touch even for business? Who has the right to change investment policy? What if one partner sees a risk and the other sees an opportunity? How will a child grow up around capital without one day only gaining access without judgment?
This is where a financial plan becomes insufficient as a single document.
In MN SAPIENS it does not disappear: the financial model becomes one of the engineering layers of the Family Welfare Plan / HFWP.
But the family has issues that don't fit into a conventional financial model. Who will carry out this plan if the main person falls out of the system? What money should you not touch even for business? Who has the right to change investment policy? What if one partner sees a risk and the other sees an opportunity? How will a child grow up around capital without one day only gaining access without judgment?
This is where a financial plan becomes insufficient as a single document.
In MN SAPIENS it does not disappear: the financial model becomes one of the engineering layers of the Family Welfare Plan / HFWP.
The family capital plan does not cancel the calculation. It puts the calculation on a stronger foundation. In it, money is connected not only with goals, but also with family life, business, risks, documents, access, tax and legal structure, continuity and development of the next generation.
A typical financial plan is built around the question: “How can I achieve my goals?” The Family Capital Plan asks the question early: “What kind of family will live up to these goals and will it sustain the journey towards them?”
A typical financial plan is built around the question: “How can I achieve my goals?” The Family Capital Plan asks the question early: “What kind of family will live up to these goals and will it sustain the journey towards them?”
If a business urgently needs money, the usual plan looks at liquidity. The Family Capital Plan asks: Is it a family reserve or a hidden business loan?
If the investment portfolio is down, the usual plan looks at the risk profile. The Family Capital Plan asks: Who in the family has the power to stop an impulsive decision?
If the child gets access to major opportunities, the usual plan considers the budget. The family capital plan asks: what has he already learned, besides the ability to enjoy comfort?
If the investment portfolio is down, the usual plan looks at the risk profile. The Family Capital Plan asks: Who in the family has the power to stop an impulsive decision?
If the child gets access to major opportunities, the usual plan considers the budget. The family capital plan asks: what has he already learned, besides the ability to enjoy comfort?
In the canon of MN SAPIENS, HFWP, the family capital plan, holds six circuits.
First: goals, cash flow and family scenarios. Not just “as much as we want,” but what life is behind it and what scenarios can change it. Second: risk management and insurance protection. Not as a set of policies, but as protection for critical family goals. Third: investment policy and portfolio architecture. Not a set of tools, but capital rules based on confirmed requirements for the family’s investment policy. Fourth: tax, legal and ownership structure. Not an illusion of control, but a clear structure of ownership, responsibility and transfer. Fifth: compliance, jurisdictions, access and international infrastructure. Not fancy bills in different places, but a functioning family infrastructure. Sixth: succession, family management and development of the next generation. Not “someday to children,” but a gradual transfer of a culture of solutions.
These six outlines should not live in different folders. If they are not connected, the family receives not a plan, but an archive of good intentions.
First: goals, cash flow and family scenarios. Not just “as much as we want,” but what life is behind it and what scenarios can change it. Second: risk management and insurance protection. Not as a set of policies, but as protection for critical family goals. Third: investment policy and portfolio architecture. Not a set of tools, but capital rules based on confirmed requirements for the family’s investment policy. Fourth: tax, legal and ownership structure. Not an illusion of control, but a clear structure of ownership, responsibility and transfer. Fifth: compliance, jurisdictions, access and international infrastructure. Not fancy bills in different places, but a functioning family infrastructure. Sixth: succession, family management and development of the next generation. Not “someday to children,” but a gradual transfer of a culture of solutions.
These six outlines should not live in different folders. If they are not connected, the family receives not a plan, but an archive of good intentions.
This is why a family capital plan cannot be built immediately after the first impression.
First, the family needs to see the living reality: where is the tension, what decisions rest on one person, what is happening with business, access, protection, children and goals. Then you need a systemic map of the family: roles, capitals, vulnerabilities, consistency, readiness for the unexpected. After this, an agreed strategic course for the family and a strategic assignment for the Family Welfare Plan / HFWP are formed: what kind of life the family builds, what protects, what rules will withstand stress and what should be passed on.
It is only on this basis that the Family Welfare Plan/HFWP becomes not a document to be filed, but an engineering execution.
First, the family needs to see the living reality: where is the tension, what decisions rest on one person, what is happening with business, access, protection, children and goals. Then you need a systemic map of the family: roles, capitals, vulnerabilities, consistency, readiness for the unexpected. After this, an agreed strategic course for the family and a strategic assignment for the Family Welfare Plan / HFWP are formed: what kind of life the family builds, what protects, what rules will withstand stress and what should be passed on.
It is only on this basis that the Family Welfare Plan/HFWP becomes not a document to be filed, but an engineering execution.
A family capital plan is not meant to make life more difficult for the family. Vice versa. It is needed so that complexity ceases to be invisible.
As long as capital grows, invisible complexity seems tolerable. But in a crisis it becomes expensive. One doesn't know where the documents are. Another doesn’t understand what money shouldn’t be touched. Business and family are fighting over the same reserve. Children see wealth, but do not see rules. Advisors give good recommendations, but each from their own corner.
The Family Capital Plan brings these angles together into one map.
As long as capital grows, invisible complexity seems tolerable. But in a crisis it becomes expensive. One doesn't know where the documents are. Another doesn’t understand what money shouldn’t be touched. Business and family are fighting over the same reserve. Children see wealth, but do not see rules. Advisors give good recommendations, but each from their own corner.
The Family Capital Plan brings these angles together into one map.
The main question is: does your family today have a financial calculation or a system that can fulfill this calculation?
We use cookies
Cookie settings
Essential cookies are always enabled because they are required for the website to work correctly.
Analytical cookies from Yandex Metrica can be enabled or disabled.
Analytical cookies from Yandex Metrica can be enabled or disabled.
